Gambling taxes in Mexico: income tax on winnings
 Play now ›
In this article
Gambling taxes in Mexico are simpler than what circulates on social media. Under the law, what you win in an authorised betting game is a prize, and the federal tax is withheld by whoever pays you. You do not have to file anything each time you cash out, but it is worth knowing how much is withheld, when that withholding is all you pay and when you have to declare it. This guide explains it with the text of Mexico’s income tax law (Ley del Impuesto sobre la Renta, ISR) in hand. It is general information, not tax advice.
What the law says: your winnings are “prizes”
Article 137 of the Ley del ISR defines the regime that applies to winners:
“Income from obtaining prizes is considered to be income deriving from lotteries, raffles, draws, betting games and contests of all kinds, legally authorised.” (our translation)
Note the last two words, “legally authorised”. This regime is designed for games that operate with a permit from Mexico’s Secretaría de Gobernación. That is one more reason, on top of your protection as a player, to check a site’s permit before depositing; our guide to legal online casinos in Mexico shows how.
How much is withheld from a betting prize
Article 138 separates two cases, and almost all the confusion comes from mixing them up:
| Type of prize | Federal ISR | Calculated on |
|---|---|---|
| Betting games organised in Mexico | 1% | Total amount distributed among all winning tickets |
| Lotteries, raffles, draws and contests, in states with no local tax or one of up to 6% | 1% | Prize value of each ticket, with no deductions |
| Lotteries, raffles, draws and contests, in states with a local tax above 6% | 21% | Prize value of each ticket, with no deductions |
Source: Ley del ISR, article 138, current text published by Mexico’s Chamber of Deputies (last amended DOF 01-04-2024).
In all three cases the tax is withheld by whoever pays the prize, so you receive the prize with the withholding already applied.
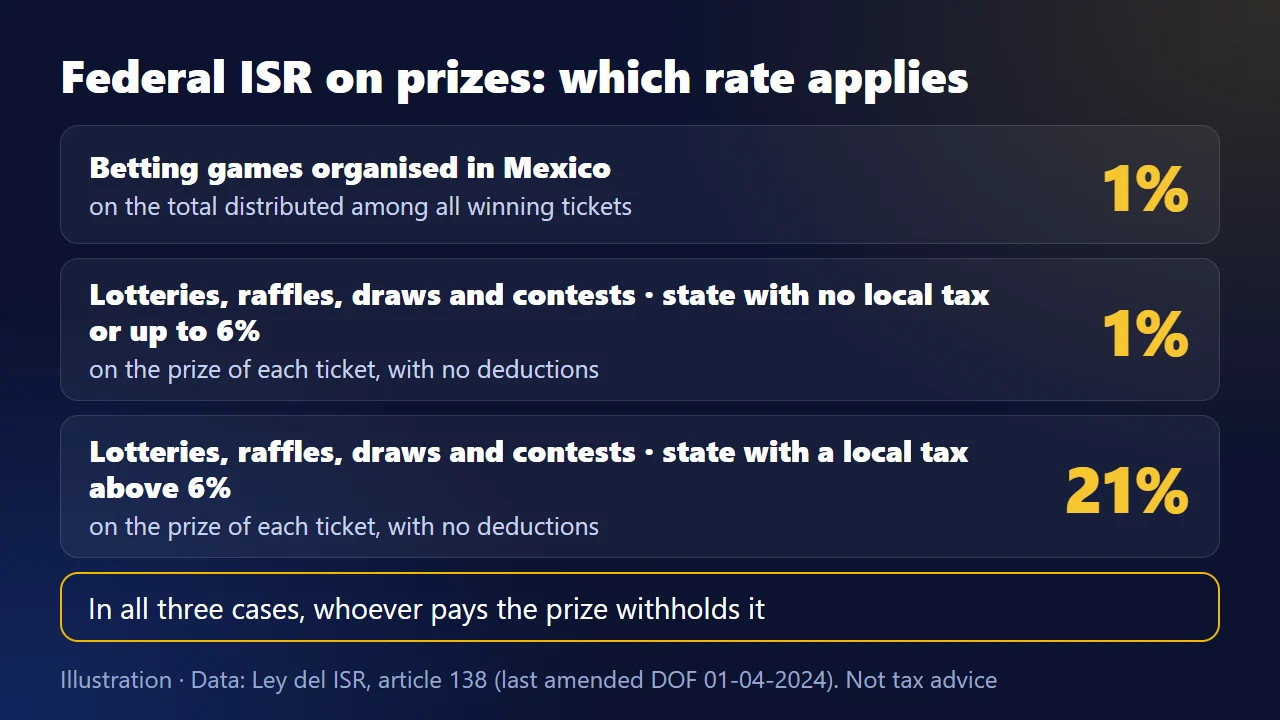
An illustration based on the table from the law: the high rate only applies to lotteries and draws in states with a high local tax.
The 21% myth
You will often read that “the SAT keeps 21% of whatever you win betting”. The law does not say that for betting games. The 21% appears in the first paragraph of article 138, which covers lotteries, raffles, draws and contests, and only in states that charge a local tax above 6%. The second paragraph, the one on betting games, sets 1%. That first paragraph is the one that applies to draws such as Melate: our guide to how to play Melate explains where each prize is claimed and when the tax is withheld.

When the withholding is all you pay
Under article 138, the withholding counts as a final payment, meaning you do not pay income tax on that prize again in your annual return. There is one condition, which comes from article 90.
- If your prizes, loans and gifts for the year add up, alone or together, to more than 600,000 pesos, you must report them in your annual return.
- If you are required to and do not report them, the withholding is no longer final. The prize is then added to your other income for the year, you calculate the tax with the annual rate table and subtract the federal tax already withheld.
If you stay below that figure in a year, the withholding is all the income tax you pay on your prizes. If you go above it, the sensible step is to talk to an accountant before filing.
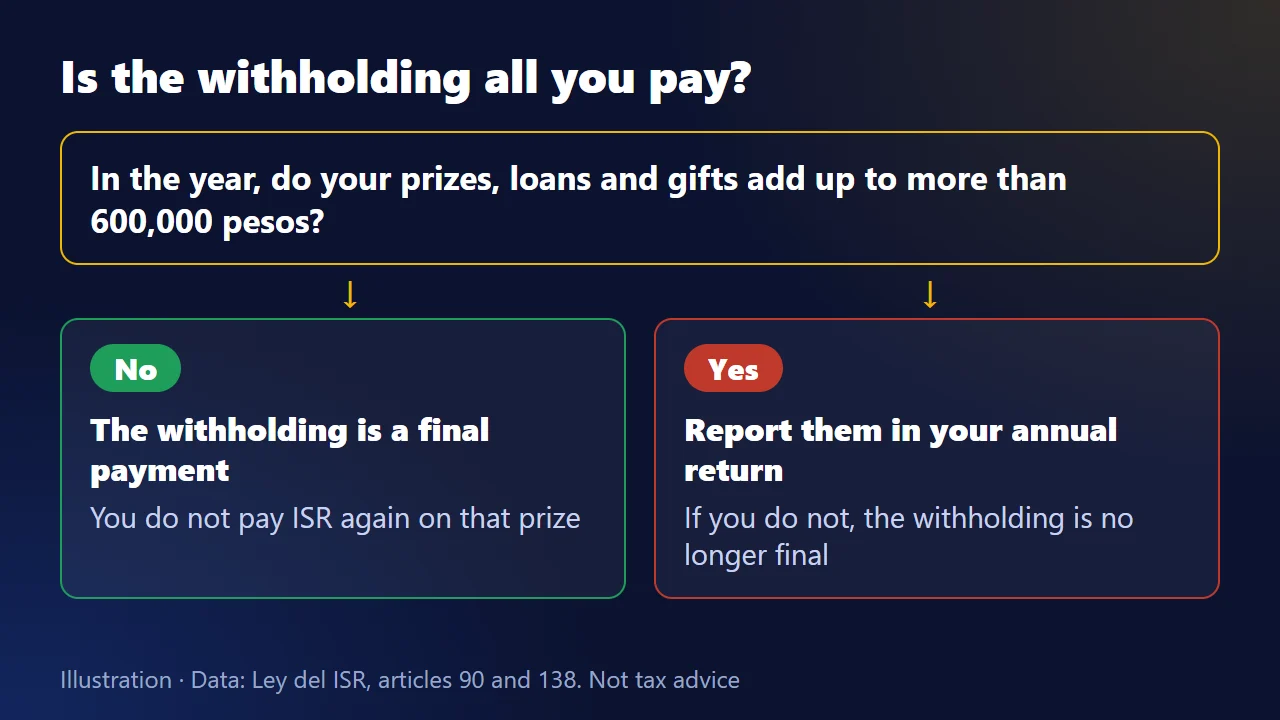
The diagram boils the legal condition down to one question; if your answer is yes, it is worth talking to an accountant.
The receipt and your state’s tax
The SAT explains on its website that if tax was withheld from a prize, whoever paid it must issue you a tax receipt (comprobante fiscal) covering the payment and the withholding. Keep it, because it proves the tax has been paid.
On top of the federal income tax, several states charge a local tax on prizes, at rates set by each state’s finance law. That is why the total deducted from a prize can vary depending on where you live.
And at JuegaLotto, what changes?
JuegaLotto operates with a permit from the Secretaría de Gobernación, so its games fall under the “legally authorised betting games” of article 137; the full permit and who runs the site are in what is JuegaLotto?. This blog cannot tell you how a withholding shows up in your account in each specific case: if you have a question about a prize or a receipt, ask JuegaLotto support with the details of the transaction.
For the practical side of cashing out, the guide on how to withdraw money covers limits, times and identity verification.
Disclaimer
This guide summarises the law in force on October 30, 2026 and is not tax advice. Laws change and every case has its details, so for a specific decision ask an accountant or the SAT itself.
Play responsibly
Knowing how much tax a prize carries does not turn betting into income. Results are random and, over time, you should expect to lose more than you win. Play only if you are 18 or over, with a budget you can afford to lose, and read our responsible gambling guide. If you need help, Línea de la Vida answers on 800 911 2000.
Sources: Ley del Impuesto sobre la Renta, articles 90, 137 and 138, current text (Chamber of Deputies, last amended DOF 01-04-2024) — https://www.diputados.gob.mx/LeyesBiblio/pdf/LISR.pdf · SAT, «Conoce el Régimen de los Ingresos por la obtención de premios» — https://wwwmat.sat.gob.mx/consulta/72905/conoce-el-regimen-de-los-ingresos-por-la-obtencion-de-premios
Frequently asked questions
How much tax does the SAT take from a betting prize?
Under article 138 of Mexico's income tax law (Ley del ISR), the federal tax on prizes from betting games organised in Mexico is 1% of the total amount distributed among the winning tickets, withheld by whoever pays the prize. Some states also charge their own local tax.
Do sports bets pay 21% income tax?
Not as a general rule. The law sets 21% for prizes from lotteries, raffles, draws and contests in states that charge a local tax above 6%. For betting games, the same article sets 1%.
Do I have to declare my betting winnings?
If your prizes, loans and gifts for the year exceed 600,000 pesos, alone or together, you must report them in your annual tax return (article 90 of the Ley del ISR). Below that figure, the tax withheld by whoever paid the prize counts as final payment.
What happens if I do not report a prize I had to declare?
The withholding is no longer a final payment: the prize is added to your other income for the year and you calculate the tax with the annual rate table, subtracting the federal tax already withheld.
Should I get a receipt for the withholding?
Yes. The SAT says that if tax was withheld from a prize, whoever paid it must give you a tax receipt (comprobante fiscal) covering the payment and the withholding.